
Methanol prices rally on shrinking supply and MTO restart expectations
Supply tightens on both fronts: August imports estimated at ~700kt (Sept ~500kt), while domestic maintenance losses hit 7 million mt/yr-both imports and production shrinking
Inventories to see temporary rebound: Port stocks plunged 111kt last week but will surge this week as delayed cargoes arrive
MTO restarts loom: Improved olefin margins have raised expectations for MTO unit restarts, which would boost methanol demand.
Cost support firm: Higher coal, crude, and energy prices underpin methanol.
Shrinking supply
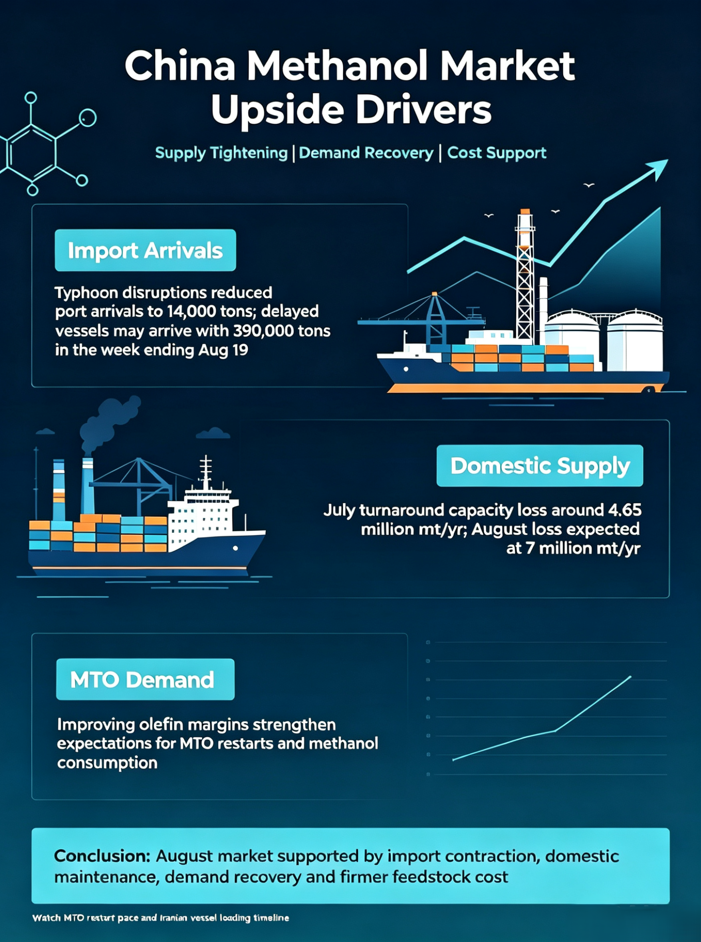
Recently, China's methanol market experienced a round of upward price movements. Last week, affected by the typhoon and port closure, methanol arrivals at Chinese ports significantly decreased to only 14,000 in the week ending Aug 12.
As a result, the tank inventory at East and South China declined sharply by 111,000 tons in the week ending Aug 13. It tightened the availability of cargoes at China's coastal market, providing strong support for spot prices.
However, the vessels originally scheduled to arrive last week were forced to be delayed and are now expected to arrive intensively in the week ending Aug 19, with weekly arrivals forecast at 390,000 tons. Tank inventories are likely to see a surge this week.
But toward the end of August and mid-September, there will be another period of reduced arrivals from the Middle East. Iranian cargo loadings in August have been very limited, and unless the U.S.-Iran situation takes a turn, the broader trend of declining cargoes to China remains unchanged.
August arrivals in China are estimated to be around 700,000 tons, while September arrivals are expected to fall back to around 500,000 tons (including Iranian and non-Iranian cargoes).
In August, apart from shrinking imports, China domestic supply is also anticipated to concurrently decline. Summer maintenance of Chinese units is concentrated in July-August, with capacity loss from domestic unit turnarounds in July reaching approximately 4.65 million mt/yr and August losses expected to hit 7 million mt/yr (excluding long-term idle capacity).
Therefore, the supply-side support for the methanol market in August is built on the combination of domestic unit maintenance and reduced imports.
Demand recovery expectation
The most critical change on the demand side in August is the notable recovery in olefin margins. As downstream olefin product prices rose, the profitability of MTO (methanol-to-olefins) units improved considerably.
This margin recovery directly strengthened market expectations for the resumption of MTO operations. The anticipated restart of MTO units has a fairly pronounced boosting effect on methanol consumption. Even if supply rebounds later, the restart of multiple MTO units and robust demand should provide support to the market.
Firm feedstock cost
Beyond the supply-demand shifts, the recent price rise was also attributed to cost-side strength. Firm coal prices and higher crude, energy and chemicals have lifted methanol's valuation. With cost support and improving fundamentals reinforcing each other, the price rally has a firmer ground.
In a conclusion, China domestic and overseas supply are both shrinking, demand side has MTO restart expectations driven by margin recovery, and methanol price is also underpinned by rising feedstock prices.
Though concentrated arrivals may temporarily boost inventories this week, the broader August import contraction remains intact. The pace of MTO restarts and the timeline for Iranian vessel loadings to resume should be watched closely.
- Top keywords
- Cotton Price
- Cotton Futures Price
- Cotton Futures
- CZCE
- PTA Futures Price
- Chemical Fiber
- Polyester Prices
- Wool price
- PTA Futures
- Shengze Silk
- China
- Yarn Price
- price
- China Textile City
- Fibre Price
- Benzene Price
- Cotton
- Index
- Cotton Index
- PTA
- fabric price
- NYMEX
- Top 10
- textile industry
- Spot Cotton
- Cotton Yarn
- Futures
- Polyester Price
- PTA Price
- cotton yarn price